US intermediary market dominated by three asset managers
Financial intermediaries recalled 499 unique asset management brands in our latest research
Key points:
- The respondents recalled 499 unique brands and provided 15,980 mentions across all 16 asset classes and management styles prompted.
- The top asset manager was mentioned at least once by 56.7% of respondents.
- On average, half of the respondents are very familiar or quite familiar with the 14 best known asset managers.
The intermediary asset management market in the US is dominated by three players, even though intermediaries recalled 499 unique brands in the latest research by Aureum Y, Fundamental Group’s research division.
This is one of the key findings from the US Global Brand Survey 2025, which is based on the responses from 1,096 financial intermediaries in the US. To understand their perception of asset managers’ brands, we have developed a Brand Equity Index using a combination of quantitative and qualitative methods across five pillars: recall, familiarity, perceived quality, propensity to buy and distinctiveness.
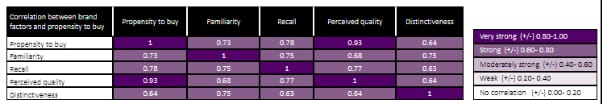
The propensity to buy score assesses the likelihood to increase the use of funds provided by that particular asset manager. When correlating this score with those from the other four brand factors, we see that US intermediaries’ belief in an asset manager’s ability to generate returns (perceived quality) is the main consideration when buying a fund. Perceived quality has the strongest correlation to propensity to buy, followed by brand recall.
The respondents recalled 499 unique brands and provided 15,980 mentions across all 16 asset classes and management styles prompted.
While almost 500 different brands were mentioned spontaneously, when looking at the proportion of mentions across the sample, the top asset manager was mentioned at least once by 56.7% of respondents, followed by 51% and 50.4% of respondents who mentioned the number two and three, respectively.
The figures show a strong dominance of these three asset managers in the US market, followed by a solid group of competitors who are well recognized for their expertise in specific asset classes or management styles.
Familiarity and distinctiveness
When it comes to familiarity, on average, half of the respondents are very familiar or quite familiar with the 14 most well-known asset managers. The top four brands are well known by more than 70% of respondents.
However, there are some stark differences in familiarity scores, showing signs of a market dominated by a leading set of brands, making it challenging for the others to gain recognition.
The score for distinctiveness as a brand factor took into consideration scores for 14 brand values. When looking at how these brand values affect the propensity to buy, US intermediaries are slightly more likely to buy funds from asset managers which they consider to be like a partner, analytical, tried and tested, and broad.
Qualitative analysis of comments on different asset managers revealed that US intermediaries provided more positive comments for those asset management firms that scored high on the brand values ‘partner’, ‘personable’ and ‘targeted’ rather than those perceived as ‘supplier’, ‘corporate’ and ‘broad’ with most of the other value sets receiving a similar number of positive and negative comments.
For full access to the reports, visit our dedicated research page.
Local managers rival globals among financial intermediaries in Switzerland
Local Swiss asset managers now match global names for brand familiarity among financial intermediaries in Switzerland. Read Aureum Y's full findings.
Financial intermediaries' media habits across five markets
New Aureum Y research reveals how financial intermediaries across five markets use social media, newsletters, podcasts and events.
LinkedIn holds social lead for asset managers in Q2 2026
LinkedIn led social posting among 40 asset managers in Q2 2026, while YouTube engagement surged in May. Fundamental Media's quarterly data analysis.